
On November 3, 2026, the Second Circuit reversed the dismissal of a Defend Trade Secrets Act claim in SS&C Technologies Holdings, Inc. v. Arcesium LLC, No. 25-2049 (2d Cir. Nov. 3, 2026) (Sack, J., joined by Livingston and Carney, JJ.). It is a very plaintiff-friendly DTSA decision; anyone who underwrites or litigates trade secret cases in this Circuit should read it. The facts are familiar. SS&C owns Geneva, a portfolio accounting platform built over decades. Arcesium licensed Geneva under a reseller agreement that barred it from using Geneva to build a competing product. While it had access, Arcesium built its own platform, Trinity, in under three years (Geneva took decades!), pitched Geneva customers on Trinity having “the same” functionality, and built a second tool, Nautilus, to keep connecting to Geneva after the license expired. Internal emails showed employees acknowledging the “IP constraints” and being told not to describe Trinity’s requirements by reference to “what Geneva does.” The Southern District of New York found that SS&C had pleaded trade secrets but not misappropriation, and dismissed. The Second Circuit reversed. The Crux: Courts Shouldn’t Pick Between Competing Readings on a 12(b)(6) Motion The most important part of the opinion is its rebuke of how the district court used certain documents attached to the complaint. Prior to filing an amended complaint, the district court had ordered Arcesium to produce 23 documents that SS&C identified as integral to its case. SS&C quoted those documents in its complaint. Arcesium then attached the same emails, plus a declaration from its Head of Technology, to its motion to dismiss and offered its own innocent explanation of what they meant. The district court accepted that explanation. The Second Circuit identified two errors: Self-serving defendant documents shouldn’t be taken as true. Citing Pearson v. Gesner, the court said that when a plaintiff incorporates a defendant’s “unilateral writing,” the court must ask why the plaintiff relied on it, not accept “every word” as true. Arcesium’s internal emails were exactly that kind of document. No fact-finding on a motion to dismiss. The “more fundamental error” was that the court weighed Arcesium’s explanation against SS&C’s allegations and decided Arcesium had “the better interpretation.” That is fact-finding. The district court relied on the rule that when an incorporated document contradicts the complaint, the document controls. The Second Circuit answered: “Perhaps.” But the documents did not contradict SS&C. The parties simply read them differently, which “is, of course, to be expected in any litigation.” Courts may look at incorporated documents, but they may not “take on the role of the jury when doing so.” This matters well beyond software. In trade secret cases, the plaintiff’s best early evidence is often the defendant’s own emails, obtained through pre-suit discovery, a related case, or a whistleblower. Defendants routinely attach those emails to a motion to dismiss and argue an innocent reading. SS&C shuts that down at the pleading stage. Sharing With Customers Under NDA Is Permissible Arcesium argued that Geneva could not be a trade secret because every licensed user had access to the executable software, the integration layer, and the data model. The Second Circuit rejected that argument because it would create “a near-blanket rule that any information shared with a third party cannot be a trade secret.” Adopting the Ninth Circuit’s view, the court held that giving trade secrets to third parties “does not undermine a trade-secret claim, so long as the information was provided on an understanding of confidentiality.” SS&C alleged that Geneva could be accessed only by licensed customers bound by strict non-disclosure and confidentiality provisions. That was enough. For any business that licenses its secret sauce, whether software, data, or processes, this is the right answer and it is now settled in the Second Circuit. Specificity: Enough to Give Notice and No More Arcesium also made the usual argument that SS&C described only “extraordinarily general categories of information.” The court declined to adopt a “general specificity rule.” Following the Third Circuit in Oakwood Laboratories v. Thanoo, it held that a plaintiff “need not spell out the details of the trade secret to avoid dismissal.” The complaint only needs to identify the secret with enough specificity to “place a defendant on notice of the bases for the claim” and let it “ascertain at least the boundaries within which the secret lies.” SS&C met that standard by doing more than listing categories. It described what each component does (for example, the database that stores portfolio, price, and transaction data) and how it is used (for example, the integration layer that lets developers run Geneva functions and move data in and out). The court contrasted that with a complaint that claimed only a “core brand and marketing plan strategy.” The lesson is to describe what the secret does and why it matters, not to disclose the secret itself in a public pleading. “Use” Is Very Broad The Second Circuit had never defined “use” under the DTSA. It now has, and the definition is expansive: “any exploitation of the trade secret that is likely to result in injury to the trade secret owner or enrichment to the defendant.” That includes marketing goods that embody the secret, relying on it to speed up research and development, and soliciting customers with it. Trade secrets “need not be exactly copied,” a product that is merely “similar” can be enough, and the court cited with approval district court cases finding use where a defendant studied the information to “increase his knowledge base.” SS&C’s allegations fit easily: Trinity was built in under three years against Geneva’s decades, Arcesium went live eight months after its CEO said a transition would take at least twelve, and it sold Trinity to Geneva customers as able to mimic Geneva’s functionality. Taken together and against the license restrictions, that stated a claim. Why It Matters The court was careful to say it was not ruling on the merits or on the right reading of the emails, and SS&C still has to prove its case. But at the pleading stage, SS&C v. Arcesium tilts the field toward DTSA plaintiffs in four ways: confidentiality agreements with customers are reasonable measures; specificity means notice, not a blueprint; “use” reaches nearly any exploitation of the secret; and courts may not credit a defendant’s spin on its own documents to end a case early. From a funder’s perspective, that matters. Early dismissal risk is one of the biggest variables in pricing a trade secret case, and this decision meaningfully reduces it for well-pleaded claims in the Second Circuit. Read the Second Circuit’s full opinion HERE . For a deeper look at how we evaluate these cases, see Certum’s Trade Secret Playbook . If you are evaluating a live dispute—or simply want to pressure-test what a matter is worth and how it might be funded—get in touch. A confidential conversation with Certum is free and carries no obligation, whether or not you ultimately seek funding. Reach us at certumgroup.com/contact-us .
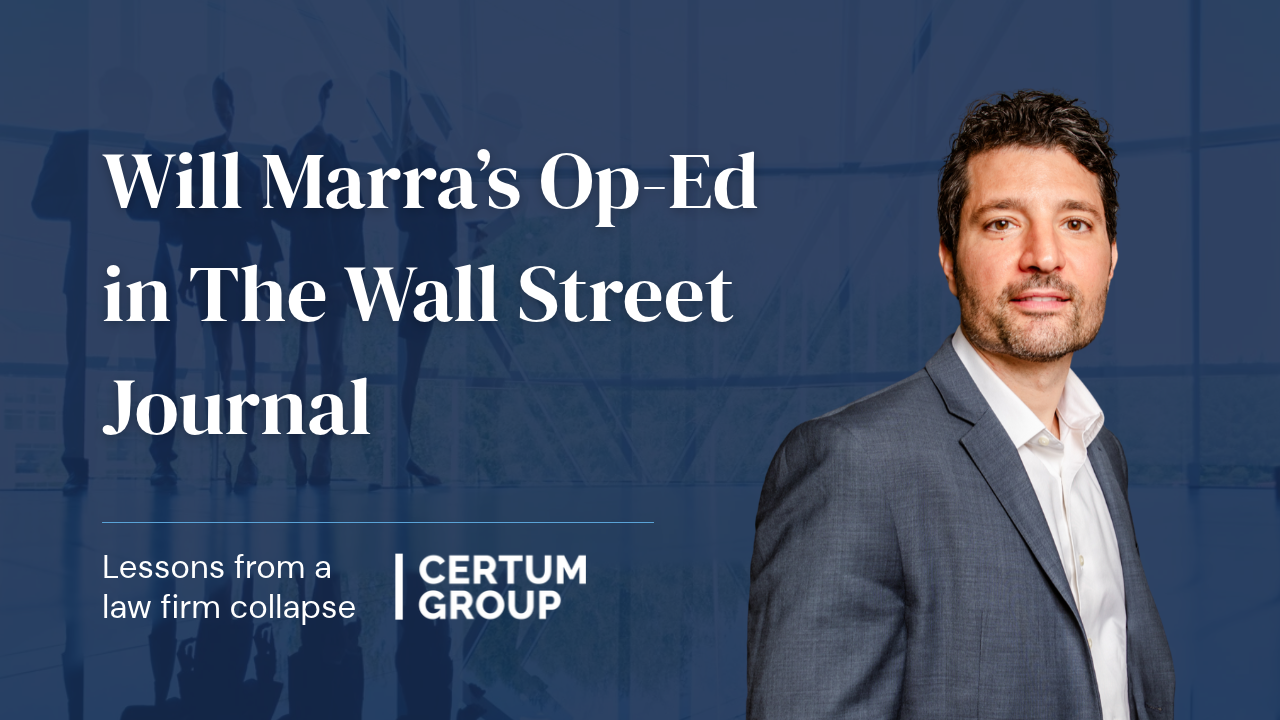
Certum’s Will Marra published an op-ed in yesterday’s Wall Street Journal drawing lessons from the recent collapse of Weil Gotshal for broader debates about third-party litigation funding and outside investment in law firms. Marra builds on scholarship by John Morley of Yale Law School, who has demonstrated that two legal ethics rules can contribute to the swift collapse of law firms. Those rules are Rule 5.4, which bars non-lawyer investment in law firms, and Rule 5.6, which bars non-competes for lawyers. Marra argues that these two rules affect every firm every day, by making it harder for them to make long-term investments that could reduce the cost of legal services, improve client service, and benefit the civil justice system. Marra suggests that reforming Rules 5.4 and 5.6 could not only help prevent the sudden collapse of the Weils of tomorrow but also improve the legal system writ large. The article is available at this link . For some of Will’s other commentary on litigation finance and the civil justice system, please see the article Litigation Finance in the Market Square , which was co-authored with Certum’s Scholar in Residence, Suneal Bedi , and was published last year by the Southern California Law Review.
This is the fifth post in Certum Group's seven-part series bringing our Trade Secret Litigation Playbook to the blog. It draws on Part V of the Playbook, Choosing Counsel and Structuring the Economics. Read or download the full Playbook here . The most common mistake I see claim holders make is also the most understandable one: they sign a law firm to a full contingency before they ever talk to a funder. A firm offering to take the whole case on contingency feels like a gift. You spend nothing, the firm carries the risk, and you share the upside only if you win. What could be wrong with that? When you look at cases side by side, quite a lot. A claim holder who engages a funder first and then hires counsel on a hybrid structure typically keeps substantially more of the recovery. To see why, start with the three ways to pay for a case. The three fee structures Hourly is the traditional model: you pay standard rates as the work is done, you own the outcome, and you bear 100% of the cost, win or lose. It fits deep-pocketed companies that want complete control, and smaller matters where alternative structures are hard to price. Full contingency puts the firm's fees entirely at risk, paid only from the recovery, usually at 33% to 40% of whatever comes in. It is attractive when you have limited capital, and the willingness of a good firm to take it is a genuine signal of merit. But it carries a real cost: that 30-to-40-percent-plus is meaningfully more than the combined economics of a hybrid or funded structure. Hybrid — shared risk — is the sweet spot for most matters between roughly $10 million and $250 million. The firm discounts its hourly rate, often steeply, in exchange for a smaller contingent premium on success. It preserves alignment while avoiding the full-contingency tax, and it becomes especially powerful when a funder pays the discounted fees, the claim holder pays nothing out of pocket, and counsel keeps meaningful upside. Why sequence changes the outcome Here is the part that sounds counterintuitive until you run the math. A 33-to-40-percent contingency leaves you with 60 to 67 cents of every recovery dollar. A hybrid structure — where counsel takes a smaller contingency, often 15 to 25 percent, layered on a discounted hourly fee that a funder pays — frequently leaves the claim holder with 50 to 65 percent after the funder's return, and sometimes more. The precise economics depend on the size and shape of the case, but the direction is robust: full contingency is rarely the cheapest path for a strong claim. Sequence matters because leverage is perishable. Once you sign a full-contingency engagement letter, the firm has effectively "bought" the case for its own investment committee, and switching firms afterward is expensive and awkward. With a funder in place and a hybrid structure available, you keep your optionality — you can hire the very best trial firm for your matter, rather than the best firm that happened to be willing to shoulder full risk. A funder's "no" is also valuable There is a quieter benefit, too. When a sophisticated institutional investor is willing to deploy non-recourse capital against your claim, that is one of the strongest external validations of case quality you can get, and counsel reads it that way. But even a decline is useful: it tells you where the weaknesses are — thin damages, a collectability problem, an identification gap — while you can still fix them, and before you have committed to a firm. Either way, you learn something you would rather know now than a year in. The sequence to consider In practice it looks like this. Retain trade secret counsel on a focused, limited-scope engagement to run an initial case assessment under privilege. While that is underway, open a confidential conversation with one or more funders, sharing the same materials. Use the funder's view — its willingness to fund, its read on damages, its suggested economics — to inform your choice of trial counsel. Then interview firms with that information in hand and propose a hybrid structure supported by the funder. Done well, the engagement letter, the funding agreement, and your preservation protocols can all be signed within the same week. None of this is a knock on contingency counsel, many of whom are excellent. It is simply a reminder that the cheapest-looking option at signing is often the most expensive one at resolution — and that a short conversation, before you sign anything, can be worth a large share of the recovery. Go deeper with the Playbook. This post covers one piece of a much larger picture. For the full framework — what the law requires, what a strong pre-filing case looks like, how damages experts value these matters, how counsel fee structures change your economics, and how litigation finance fits in — read Certum Group's Trade Secret Litigation Playbook , our field guide for business owners and the counsel who advise them: certumgroup.com/the-trade-secret-playbook . And if you are evaluating a live dispute — or simply want to pressure-test what a matter is worth and how it might be funded — get in touch. A confidential conversation with Certum is free and carries no obligation, whether or not you ultimately seek funding. Reach us at certumgroup.com/contact-us .